
China's AI Companies Race to Crack Japan's $172B Content and Enterprise Market
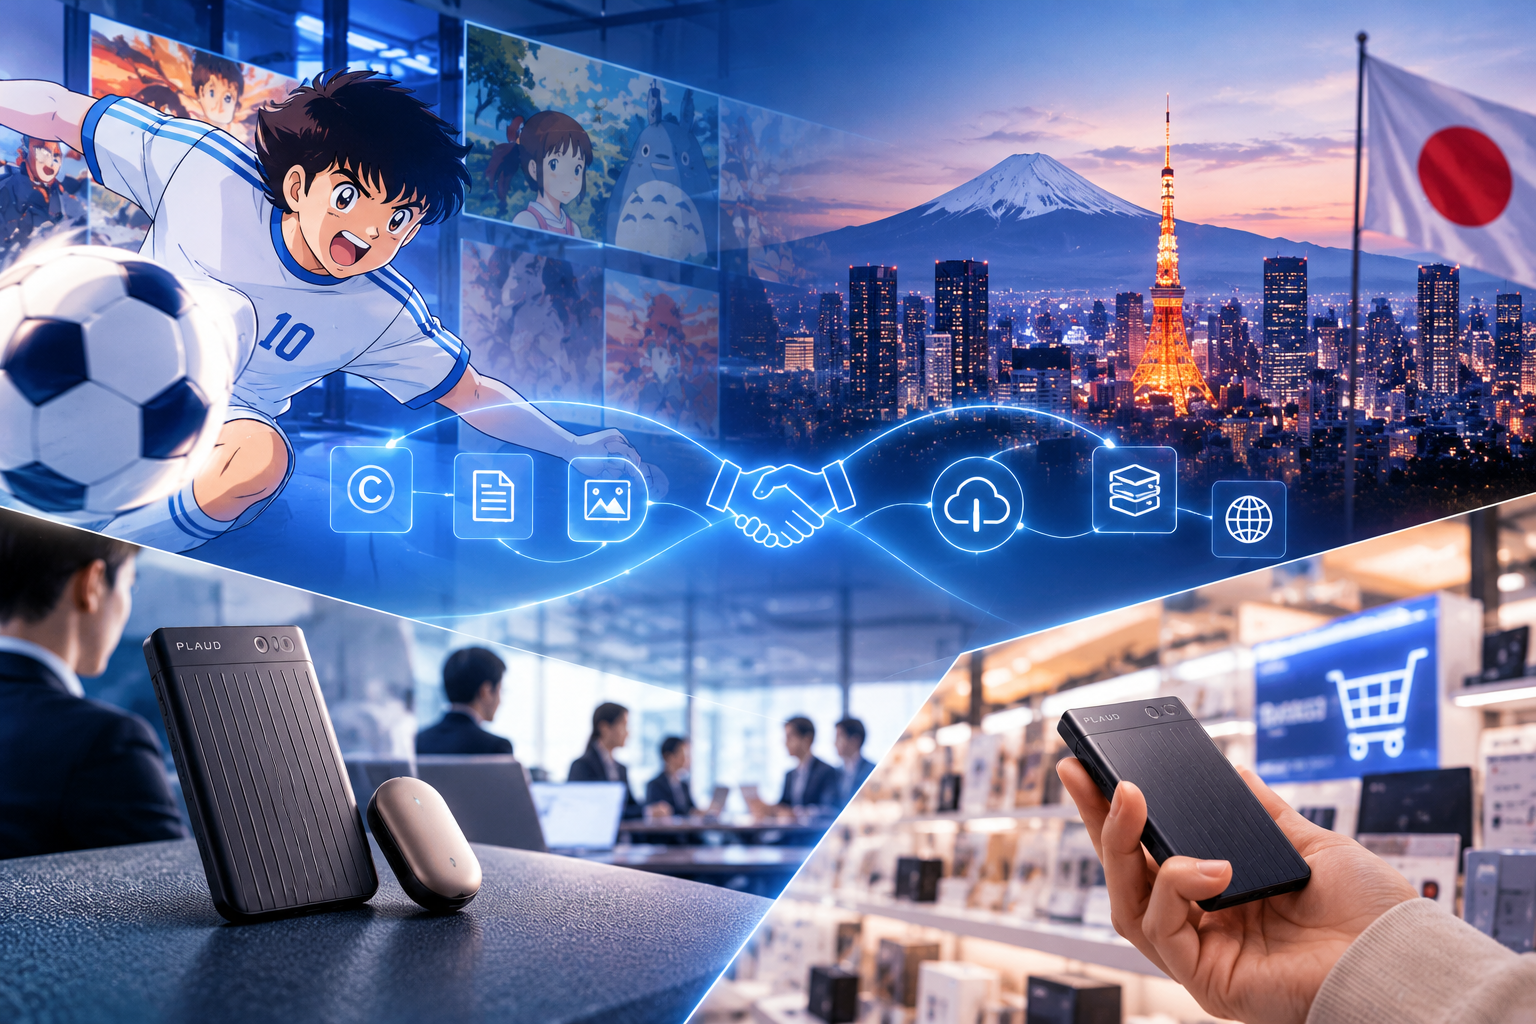
MiniMax, PLAUD, and Notta are executing three distinct market-entry strategies in a country where OpenAI stumbled—and where a 3.7x surge in government AI spending is reshaping the competitive window.
Japan's AI adoption paradox—58.8% generative AI utilization versus China's 93.6% and the United States' 75.6%—has created an asymmetric opportunity that Chinese artificial intelligence companies are moving to capture before domestic Japanese challengers emerge, armed with JPY 1.239 trillion (approximately US$172 billion) in combined government AI and semiconductor spending for fiscal year 2026.
The opening shot came on September 11, 2026, when MiniMax, a Shanghai-based AI model developer, formalized its Japan market entry at Tokyo's Nexus Square building in Shibuya, unveiling a licensing architecture designed specifically to neutralize the IP-rights objections that forced OpenAI into a months-long standoff with Japan's content industry cartel. With AKB48 producer Yasushi Akimoto in the front row and representatives from more than 150 Japanese and American enterprises in attendance, the event marked the most deliberate strategic alignment between a Chinese AI firm and Japan's notoriously protective intellectual-property establishment.
OpenAI's Sora 2 Crisis Creates the Entry Vector MiniMax Exploits
The structural opportunity MiniMax is targeting has its origins in October 2025, when OpenAI launched Sora 2. Within days, social platforms flooded with AI-generated footage imitating Dragon Ball, Bleach, and Spirited Away—content that triggered a response no Silicon Valley company had faced at this velocity or coordination.
On October 10, 2025, three Japanese cabinet ministers issued public warnings in a single day. Makoto Kichuchi, Minister of State for Intellectual Property and AI Strategy, called anime and manga Japan's "irreplaceable treasures." Digital Minister Takaaki Taira ordered compliance with Japanese regulations. Akihisa Shiozaki, a Liberal Democratic Party lawmaker and attorney, warned of a potential government investigation under Article 16 of Japan's AI Promotion Act.
Seventeen days later, on October 27, CODA—the Content Overseas Distribution Association, representing Studio Ghibli, Bandai Namco, Aniplex, Square Enix, KADOKAWA, and Shueisha—submitted a formal demand letter to OpenAI with two blunt requirements: cease using member content to train Sora 2; respond honestly to infringement complaints.
The episode exposed a fault line that runs through all of Japan's AI adoption challenge. Japan's animation production model relies on "seisaku iinkai" (製作委員会), multi-stakeholder production committees in which broadcasters, publishers, toy manufacturers, music companies, and advertising agencies all hold fractional IP rights. No single party can authorize AI training use independently. The opt-out model—Silicon Valley's default assumption that all web content is available for training unless explicitly excluded—is operationally incompatible with this structure.
MiniMax's strategic reading of this dynamic is precise: the threat is not legal resistance but structural impossibility. Opt-out cannot function where consent requires consensus among five to ten counterparties per title.
MiniMax Bets on Opt-In Architecture as Competitive Moat
MiniMax's Japan strategy centers on becoming the first AI company to embed an opt-in licensing and revenue-sharing mechanism directly into an API product layer.
The mechanism operates as follows: MiniMax co-published the Global IP·AI Co-Creation Declaration with the newly established Japan IP·AI Co-Creation Association—chaired by Takaaki Kondo of NEXYZ.Group—which provides institutional endorsement. The association's Kagami Gate platform handles rights verification and revenue distribution. On top of this infrastructure sits the MiniMax H3 IP Edition, a licensed version of MiniMax's H3 open-source video generation model through which users can legally generate new content featuring contracted IP characters.
Captain Tsubasa, the soccer manga that debuted in 1981 and whose protagonist Tsubasa Ozora has shaped the football imagination of generations across Asia and Europe, is among the first franchises entering this system. The September 11 event featured an AI-generated Tsubasa goal sequence—a scene that does not exist in the 1983 original animation—as a live demonstration of the pipeline.
The competitive significance is twofold. First, MiniMax is participating in rule-writing at the formation stage of Japan's AI-IP governance framework, a position that will be structurally harder to replicate once standards solidify. Second, by open-sourcing H3 while simultaneously offering a rights-cleared commercial version, MiniMax is positioning the licensed edition as the compliance answer to an otherwise uncontrollable proliferation problem: any user with a consumer-grade GPU can already generate Tsubasa-like footage locally using open-source models, leaving rights holders with no enforcement leverage. The IP Edition turns that vulnerability into a distribution channel.
PLAUD Sidesteps B2B Gatekeepers by Winning Individual Buyers First
While MiniMax is navigating Japan's institutional complexity from the top down, AI audio hardware company PLAUD has demonstrated that consumer electronics channels can achieve enterprise penetration through a different vector entirely.
In March 2026, Japan national football team veteran Yuto Nagatomo—the player with the most caps in the squad's history—appeared in a television advertisement wearing PLAUD's NotePin, a shirt-pocket AI recording device. The product line is straightforward: the Note Pro, a card-format conference recorder priced at JPY 30,800 (approximately US$4,280 at reference rate), and the NotePin S, priced at JPY 28,600 (approximately US$3,972). Functionality covers recording, transcription, and summarization.
The channel strategy is unambiguously consumer: Amazon Japan, Rakuten, Bic Camera, Yodobashi Camera, Yamada Denki, and Edion. PLAUD's retail footprint expanded from approximately 280 stores at end-2024 to 1,000 stores by August 2026—a 3.6x increase over 20 months.
Japan is now PLAUD's second-largest market globally. Sensor Tower data profiles the core buyer as males aged 35–55: corporate managers, attorneys, consultants, financial professionals, and healthcare practitioners. These are individual purchases that bypass corporate procurement, yet the net effect is AI infrastructure entering enterprise workflows through the consumer door.
The logic inverts the conventional B2B sales motion. Rather than negotiating with IT departments, legal, and finance over 12-to-18-month procurement cycles—a process that historically disadvantages foreign vendors unfamiliar with Japan's nemawashi consensus-building culture—PLAUD's buyers make autonomous decisions, then create internal demand for team licensing once colleagues observe the product in use.
Notta Demonstrates the SEO-Led PLG Playbook in Japanese B2B SaaS
A third model is being executed by Notta, an AI speech-to-text SaaS platform operated by Shenzhen-based Siwei Xunhang Technology. The company was founded in June 2020; its co-founder Zhang Yan previously co-founded Mobike. Notta has operated exclusively in international markets since inception, with Japan as its earliest and largest regional deployment.
Notta established a Tokyo legal entity in May 2022. As of August 2026, the platform reports more than 15 million registered users globally and over 5,000 enterprise clients. The Japan go-to-market sequence followed a product-led growth (PLG) structure: organic search optimization targeting Japanese-language keywords around meeting transcription; viral spread as individual users shared meeting summaries with colleagues; natural conversion into team and enterprise tiers as group workflows created shared-account, billing, and data-ownership requirements; local sales, customer service, and procurement support layered on as enterprise demand materialized.
The Notta case validates a sequencing hypothesis relevant across Chinese AI SaaS entrants: in a market where cold outbound sales and reseller negotiations carry high friction, SEO-driven individual user acquisition can generate enterprise pipeline at structurally lower customer acquisition costs than traditional B2B sales motions.
Government Spending Surge Opens Window, But Also Accelerates Domestic Competition
The macro tailwind is substantial. Japan's Ministry of Economy, Trade and Industry has allocated JPY 387.3 billion (approximately US$53.8 billion) for AI-specific programs in fiscal year 2026, with total AI-plus-semiconductor combined spending reaching JPY 1.239 trillion (approximately US$172 billion)—a 3.7x increase year-over-year.
This capital is mobilizing two countervailing forces for foreign entrants. On the opportunity side, Japan's large enterprises and government agencies are entering the AI procurement market with new budgets, a portion of which will flow to foreign vendors including Chinese companies. Japan's Ministry of Internal Affairs and Communications' July 2026 White Paper on Information and Communications documents that the four dominant generative AI products among Japanese users are ChatGPT (36.2%), Gemini (25.0%), Microsoft Copilot (13.3%), and Claude (4.3%)—Japan has no domestically developed large model among the top four.
On the competitive threat side, METI's GENIAC-PRIZE 2026 is offering JPY 1 billion (approximately US$139 million) in prize funding for new foundation model development, and SoftBank-backed Noetra has already secured a position in the government base model program. Japan's generative AI startup ecosystem, which was largely absent from global rankings for the past five years, is entering an accelerated formation phase.
The historical parallel from B2B SaaS is instructive and cautionary. Between 2010 and 2020, Salesforce, Workday, Slack, and Zoom established dominant positions in Japan's enterprise software market while Chinese SaaS companies were focused almost entirely on domestic demand. By the time Chinese SaaS began internationalizing around 2020, Japan's large enterprises had built stable technology stacks around American vendors. Switching costs made re-entry a decade-long proposition. In Japan's B2B technology market, being second is frequently equivalent to being absent.
Local Trust Remains the Decisive Variable
Academic frameworks for understanding Japan's market structure remain operationally relevant. Social anthropologist Chie Nakane's concept of "ba"—organizational belonging as primary identity—describes a decision-making environment in which formal meetings ratify consensus already achieved through private nemawashi consultations among all stakeholders. Foreign enterprises that arrive expecting a single decision-maker routinely misread the process.
The enterprise partnership model that has proven most durable reflects this reality. In March 2025, Perplexity transferred the entirety of its Enterprise Pro sales in Japan to SoftBank, whose 7,000-person sales force validated the product internally for six months before customer-facing deployment. This represented Perplexity's first complete sales outsourcing to a local partner in any global market. The playbook is not new: Snowflake signed a Japan distribution agreement with Hitachi Solutions in 2021; Salesforce has maintained NTT Data as its core Japan partner for years.
For Chinese AI companies now entering Japan, the question is not whether the opportunity exists—the data on adoption gaps, government spending, and IP-framework formation suggests it does—but whether they can execute the local trust infrastructure required before the government spending surge produces a new generation of domestic competitors capable of capturing their natural home-field advantage.
The window is open. The precedents suggest it will not remain so indefinitely.
Related Coverage:
ByteDance Escalates AI Overseas Push With Workplace Agent and Daily Active Users Surge
Kimi's Overseas Revenue Surpasses Domestic Sales as AI Startup Targets Global Productivity Market