
The "Labubu" Effect: Why Bank of America Sees an 80% Upside for Pop Mart as Chinese IP Conquers Manhattan
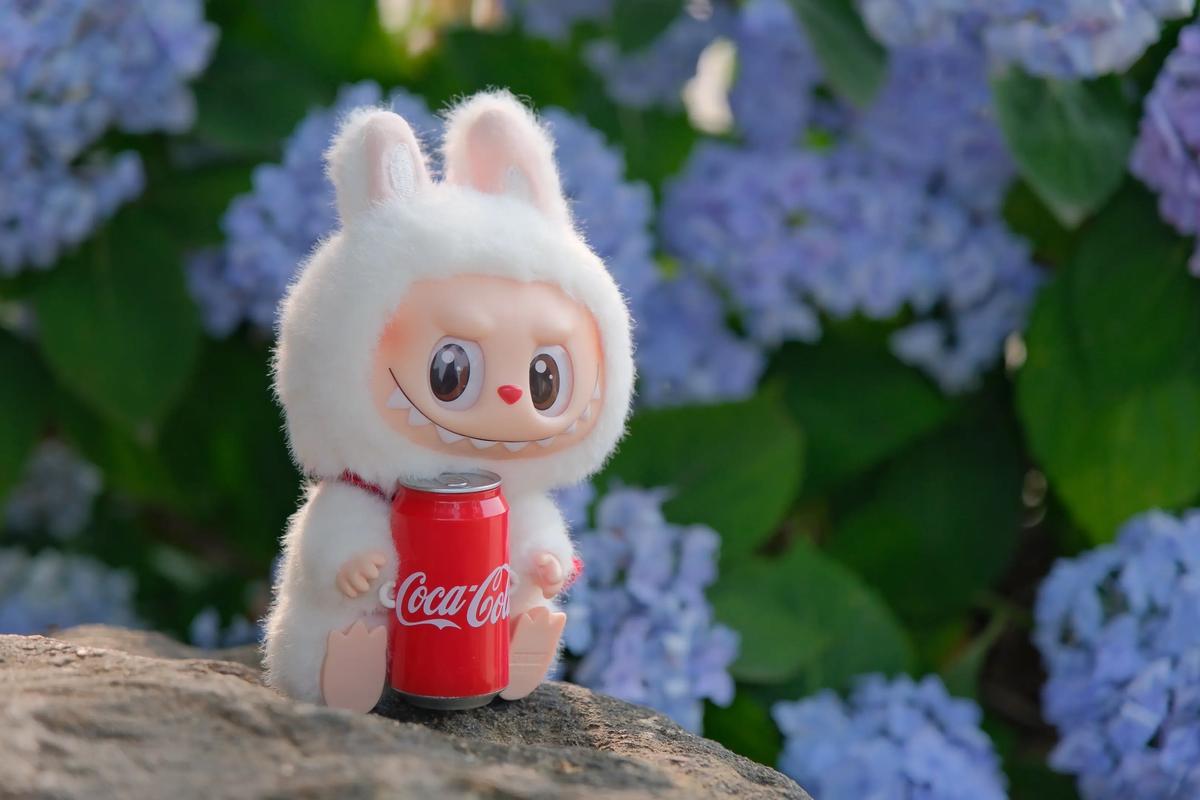
In a market often paralyzed by skepticism regarding consumer discretionary spending, a fascinating contrarian signal has emerged from Bank of America Securities. While the street has been busy selling off shares of Pop Mart—sending the stock tumbling 35% from its August peak—BofA analysts are doubling down.
In a research note released on November 27, 2025, the bank maintained a high-conviction "Buy" rating on the Chinese toy giant, slapping a price objective of HK 400 on the stock. With shares currently trading around HK 221, this implies a staggering upside of over 80%. The catalyst? A small, jagged-toothed monster named "Labubu" that is currently taking New York City by storm.
For professional investors looking past the noise, the disconnect between Pop Mart’s retreating share price and its accelerating global IP dominance presents a classic mispricing opportunity.
The Manhattan Invasion
The crux of the BofA bullish thesis lies in the visible success of Pop Mart's Western expansion. What was once dismissed by critics as a localized Asian fad is proving to have serious global legs. The report highlights the company's aggressive and successful marketing blitz during the critical US holiday season.
According to the analysts, the momentum in the US equity market has "emerged as a new highlight," specifically pointing to the cultural penetration of Pop Mart's characters during Thanksgiving week:
"Post its attendance of Macy’s Thanksgiving Parade, the rising presence of Labubu costume performance in New York garnered fresh new social media buzz. Over the week, Labubu has showed up at the Empire State Building, NBA game, and on-street activation with KOLs. Since 4Q25, the company has strategically introduced more IP offline initiatives, including Skullpanda pop-up Store in NY, and collaboration with Wednesday."
This is not merely about selling plastic toys; it is about IP stickiness. BofA argues that this "proactive ramping-up of IP operation" in the US is the core competency that will put a floor under the company's 2025 earnings and dispel the gloom surrounding 2026.
Debunking the "One-Hit Wonder" Myth
The recent sell-off in Pop Mart has been driven largely by fear—specifically, the fear that the "Labubu" craze is a cyclical peak that will vanish by 2026. The market hates unpredictability, and the lifecycle of toy trends is notoriously difficult to model.
However, BofA suggests the bears are missing the forest for the trees. The analysts describe the concerns regarding 2026 growth as "overstated," noting that the company is not dependent on a single lucky strike but operates a diversified platform with a "double-sided network effect."
"Even though we cannot precisely tell the lifecycle of Labubu IP, we believe the core value of Pop Mart still lies in the company’s IP platform ability... Labubu’s contribution was only at c.35% of total as of 1H25, and several other IPs (such as Skullpanda, Dimoo, Molly) having recorded strong popularity even before Labubu became popular. As such, we attribute the popularity of Labubu to an outcome of continuous sufficient IP operation, instead of random success (as perceived by some bears)."
A Valuation Cushion with Massive Growth
From a fundamental perspective, the risk/reward profile at current levels appears heavily skewed to the upside. The market is pricing the stock as if growth is about to collapse, yet the financials tell a story of rapid expansion.
BofA projects the company will generate a net profit of RMB 18 billion yuan (US$2.48 billion) in 2026. Despite this, the stock is trading at a pedestrian valuation for a high-growth tech/consumer hybrid and implies a PEG ratio of less than 1x—significantly cheaper than its global peers.
"In our view, the current valuation implies attractive risk/reward, with the stock trading at only 15x 2026E P/E... with 34% net profit CAGR during 2025-27E."
The Short Squeeze Setup
Perhaps the most intriguing aspect of the note is the observation on market positioning. Sentiment is currently washed out. Institutional interest on the long side has been "tepid," while short sellers have been piling in following the Q3 report.
This creates a coiled spring dynamic. With the stock down significantly from its highs and policy tailwinds beginning to swirl in China, any positive holiday data from the US could trigger a sharp reversal.
"On the flows side, we believe short-side interest has been rising post 3Q25, along with tepid interest for long-side... The stock has fallen 35% from its Aug peak (vs HSI: +3%), and we expect recovery of market sentiment (such as the new policy on China’s plan to boost consumption) as an early trigger."
While the market frets over the longevity of a monster doll, Bank of America sees a rare global platform trading at a discount. If the "Labubu" mania in Manhattan translates to the bottom line as expected, the path to HK$400 may be faster than the skeptics imagine.