
The "Toyota" of the EV War? HSBC Sees 33% Upside in Stellantis-Backed Leapmotor as Breakeven Looms
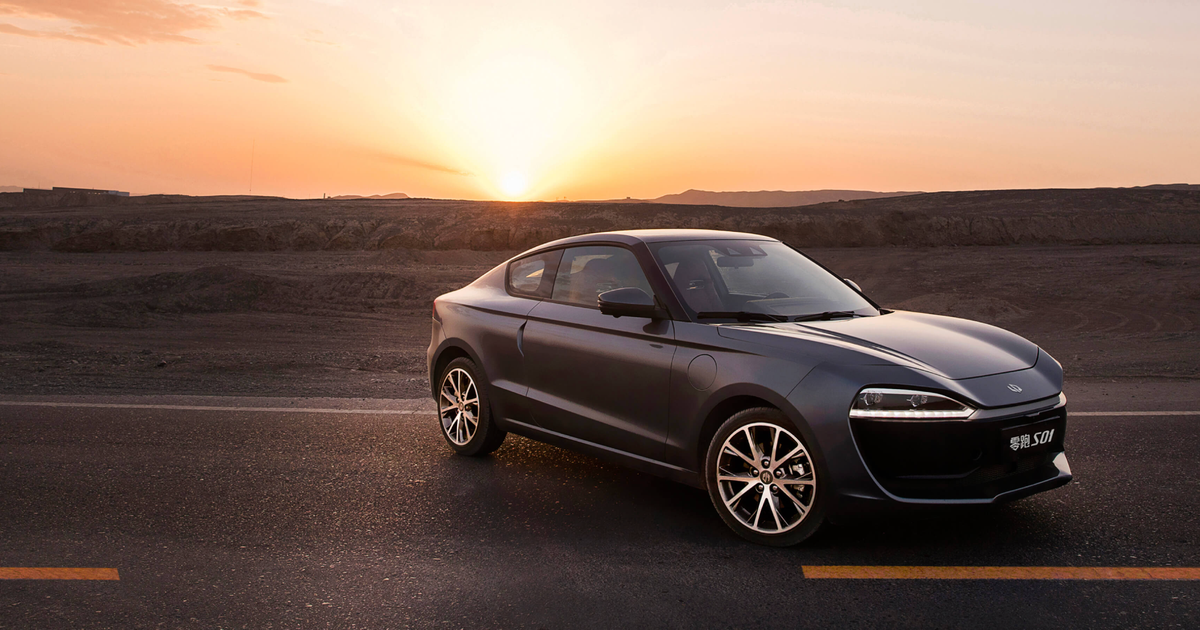
In the brutal arena of China’s electric vehicle market—where "survival of the fittest" has evolved from a cliché into a daily operational reality—profitability has long been the elusive holy grail. While headlines often chase the bleeding-edge autonomous tech of premium players, a more pragmatic winner is emerging from the bloodletting.
On November 27, 2025, HSBC Global Research initiated coverage on Leapmotor Technology International with a "Buy" rating and a target price of HKD 66.70, implying a robust 33% upside. The thesis is refreshing in its simplicity: in a macro environment defined by consumer caution, the company that masters the "value for money" segment while controlling its own supply chain wins.
With the stock down 26% over the past three months amid broader sector jitters, the bank argues this correction offers an attractive entry point into what is fast becoming the sixth-largest force in China’s domestic EV market.
The Sweet Spot: Budget Smart EVs
The overarching narrative for 2025 is not about who has the fastest 0-to-60 time, but who can survive the end of subsidies. HSBC notes that Leapmotor has successfully positioned itself just behind Tesla and BYD Company by targeting the budget-conscious consumer.
The bank’s analysis highlights a deliberate strategic pivot toward the mass market:
"It’s secret? A laser-like focus on affordable, well designed, entry-level cars with all the essential smart specs that appeal to budget conscious people, particularly in lower-tier cities. This value for money strategy is very much in line with current auto demand in China."
The numbers validate the strategy. In the first ten months of 2025, Leapmotor’s sales volumes surged 123% year-over-year, capturing 4.2% of the domestic EV market. While competitors fight for the premium scraps in Tier 1 cities, 80% of Leapmotor’s sales are driven by Tier 2 to Tier 5 cities, where practicality outweighs prestige.
Vertical Integration: The Margin Defender
In an industry plagued by supply chain bottlenecks and margin compression, Leapmotor’s approach echoes the early dominance of legacy giants like Toyota. The company doesn't just assemble cars; it builds them from the chipset up.
HSBC points to the company’s "high level of vertical integration" as the key driver for its agility and cost structure. Leapmotor manufactures approximately 65% of its vehicle bill of materials (BOM) in-house, covering everything from battery packs to smart cockpit systems.
"The company is strong on in-house R&D and has manufacturing capabilities across electronic/electrical architecture, smart driving/cockpits, battery packs, and battery management systems... This lets Leapmotor adapt quickly to market trends, while in-house control over core technologies and production underpins margins."
This discipline is expected to pay off imminently. HSBC forecasts the company will reach breakeven in 2025—a milestone that continues to elude many of its "pure-play" rivals.
The Stellantis Hedge
Perhaps the most significant differentiator for Leapmotor is its capitalization table. The company is 21% owned by Stellantis N.V., a partnership that creates a unique "asset-light" channel for global expansion.
While Chinese EVs face mounting trade barriers in the West, Leapmotor is effectively bypassing the heavy lifting of building overseas infrastructure by leveraging Stellantis’s global network.
"Although its European prices are nearly three times higher than in China, Leapmotor remains competitive; in 10M25, overseas sales were more than triple that of full-year 2024."
Furthermore, the partnership is already yielding cash. A carbon credit transfer agreement with Stellantis contributed between RMB 200 million to RMB 300 million yuan (US27.6milliontoUS27.6milliontoUS41.4 million) to revenue in the first half of 2025 alone.
Financial Outlook: Valuation Disconnect
Despite the operational momentum, the market seems to be pricing Leapmotor based on general sector sentiment rather than fundamentals. The stock is trading at a forward price-to-sales (P/S) ratio of just 0.7x for 2026, significantly below the historical average.
HSBC projects a blistering revenue CAGR of 50% from 2025 to 2027, driven by a turnover in the product cycle and the introduction of the premium D-series models in 2026.
"We forecast a net profit CAGR of 173% for 2025-27. Our 2026 earnings forecasts are 10% above consensus... In our view, the correction creates an attractive entry level as Leapmotor’s superior value proposition should support strong growth against a backdrop of budget-conscious consumers."
The bank estimates 2026 revenue to hit RMB 114.32 billion yuan (US15.8billion), with the company planning to invest RMB 50 billion yuan (US 6.9 billion), in intelligent technology R&D through 2030.
Conclusion
As the "survival of the fittest" phase in China's auto sector claims more victims, investors are looking for safety in numbers—specifically, sales numbers and margin control. With a breakeven year on the horizon and the backing of a global auto giant, Leapmotor appears poised to transition from a startup scramble to a sustainable volume player. For investors willing to weather the volatility of the Chinese market, HSBC suggests the current discount provides a compelling opportunity to buy the dip.